All Categories
Featured
Table of Contents
A post by Alexander Rugaev, the Founder of AR Ventures. Expert system has quickly end up being the main destination for international equity capital. Aggregated data from PitchBook, CB Insights, and other market trackers reveals that AI business raised roughly $270 billion in 2025, representing over half of global endeavor capital investment that year.
Why Localized Data is Essential for Saudi ML SuccessMuch of the worldwide discussion around AI investment focuses on generative designs and the huge computing facilities needed to train them. Energy availability, regulative structures, and access to long-term capital significantly form the location of AI development.
The area combines relatively low energy expenses, collaborated state-backed investment cars, and a startup community that stays less saturated than major Western markets. Together, these factors are starting to shape a various investment thesis for AI in the region. The quick growth of AI workloads is currently producing infrastructure challenges worldwide.
While capital and hardware availability remain crucial, energy supply and grid capacity are emerging as critical restrictions in numerous markets. In parts of the United States and Europe, increasing energy costs, grid restrictions, and regulatory approval timelines are starting to affect how quickly hyperscale data centres can be released. The Gulf area operates under different structural conditions.
Evaluating Modern Software Solutions and Tools
Qatar, for instance, has been actively attracting hyperscale infrastructure financial investment, while Saudi Arabia has taken a more expansive method. The kingdom's Humain effort, backed by the Public Investment Fund and partnered with business including Nvidia, AMD, AWS, Qualcomm, and Cisco, targets 1.9 gigawatts of data center capability by 2030, with longer-term aspirations of reaching 6 gigawatts by 2034.
Nevertheless, facilities investment in AI is not just a concern of capacity. Modern AI accelerators can draw close to one kilowatt of power at peak load, meaning that the long-term economics of data centres depend heavily on sustained work and energy performance. For investors, this places increasing importance on cooling innovations, energy optimisation, and the utilisation economics of reasoning work rather than simply headline capacity figures.
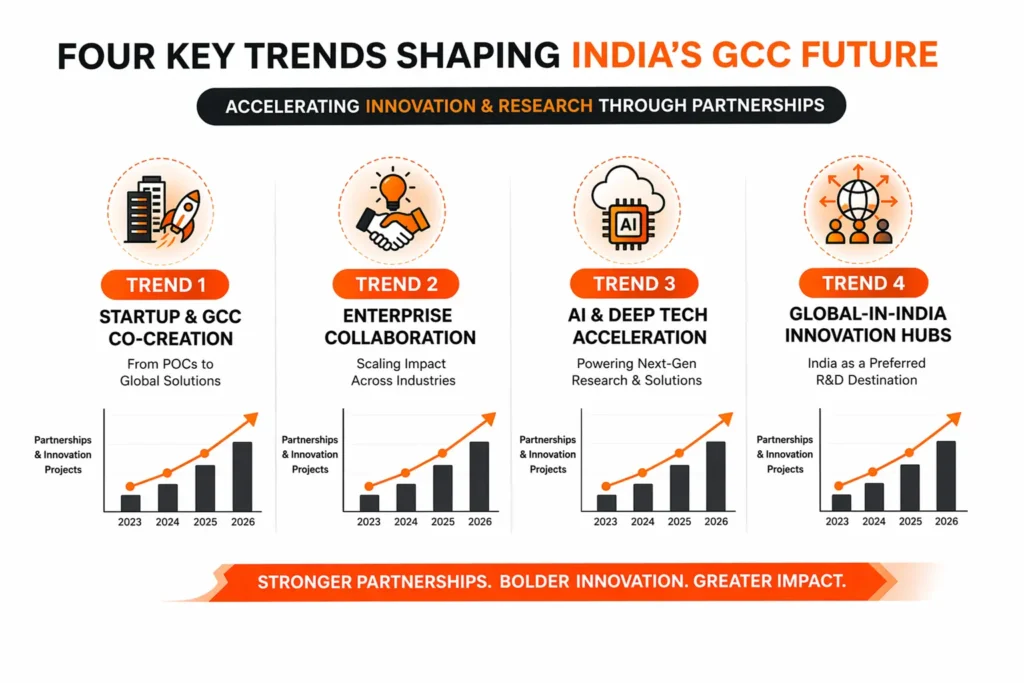
This is where the GCC may hold a benefit that is frequently neglected in international AI discussions. Across the region, governments are actively integrating AI into public administration, healthcare systems, urban preparation, and financial services. The UAE's national AI strategy, for example, prioritises the adoption of AI throughout several government departments and sectors.
AI-driven tools for credit assessment, compliance tracking, and scams detection need to operate within regulative structures shaped by Islamic finance concepts. Solutions built for these environments need specialised knowledge of regional regulative and financial systems that global startups may find challenging to duplicate rapidly. Comparable opportunities exist in other sectors. AI tools that transform clinicians' voice recordings into Arabic-language medical documentation, or systems developed to automate regulatory compliance for GCC-specific structures, resolve extremely practical operational issues.
From an investment viewpoint, startups operating in these specialised sectors often face less competition than equivalent companies in the United States or Europe. Numerous of the innovations developed for Arabic-language environments or region-specific regulative systems might also discover need in underserved markets across Africa and parts of Central Asia, where similar linguistic and regulative conditions exist.
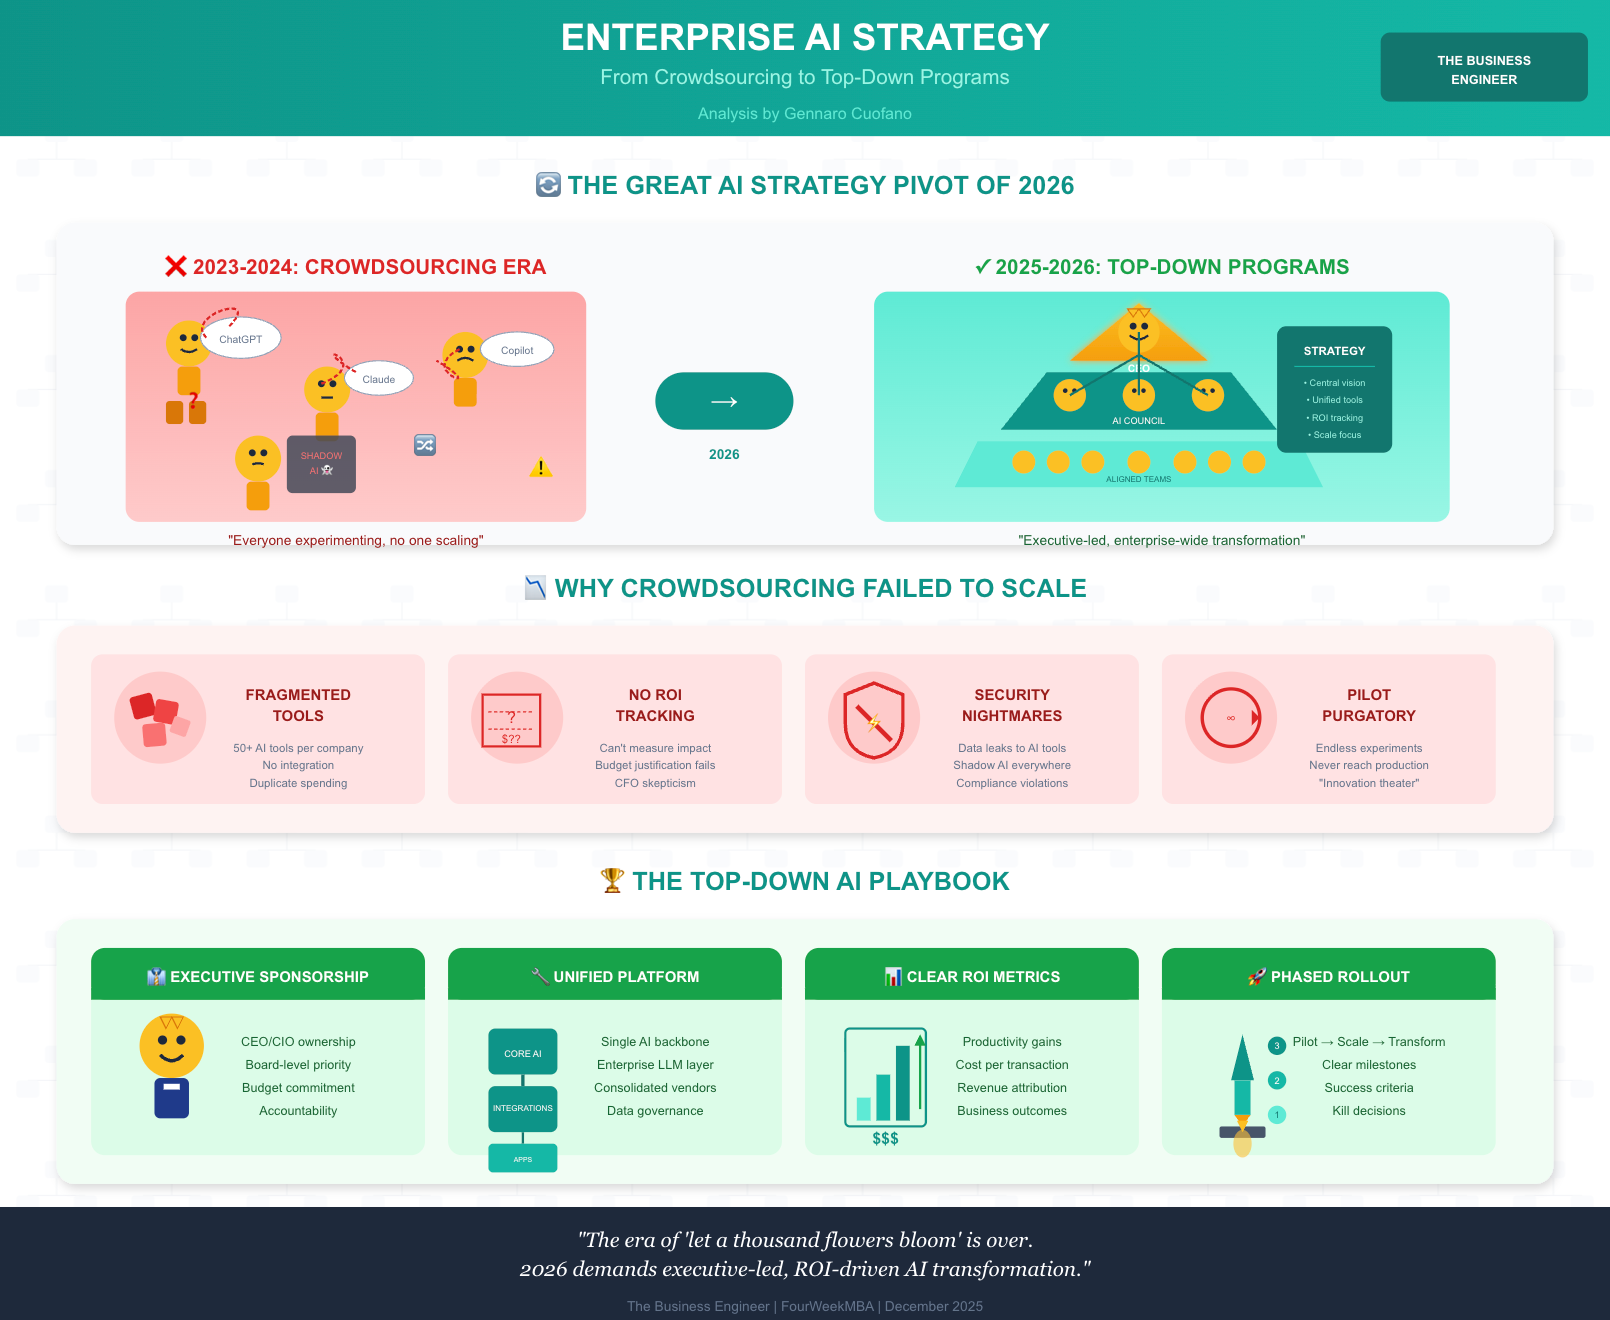
Building the Impactful AI Strategy for 2026
Infrastructure investments must be examined not just by announced data centre capacity however also by energy effectiveness, utilisation rates, and long-term work sustainability. Second, a few of the most resilient AI services may emerge from business embedded in functional workflows rather than consumer-facing applications. Enterprise software that silently automates compliance, documents, logistics optimisation, or financial analysis often generates steady, repeating income due to the fact that organisations depend on it for everyday operations.
As language designs, speech acknowledgment systems, and business AI tools end up being more customized to Arabic-speaking markets, the companies building these capabilities might ultimately serve a much broader location where similar linguistic barriers exist. As regional information centre facilities broadens and enterprise adoption of AI moves from pilot projects to large-scale procurement, the Gulf's position in the worldwide AI ecosystem might start to develop.
The structural conditions that enable this shift are already emerging: access to energy resources, collaborated capital implementation through sovereign funds, and a regulatory environment where federal governments are actively motivating AI adoption. The concern for financiers is less whether these conditions exist and more how quickly capital and creators relocate to develop within them before the opportunity becomes extensively acknowledged.
Why Advanced AI Is Vital for Modern Growth
Artificial intelligence has rapidly become the main destination for worldwide endeavor capital., accounting for more than half of international endeavor capital investment that year.

Latest Posts
The Future of Technological Innovation for Startups
New Venture Updates From GCC Startup Sector
Strategic Benefits of Cloud Integration in the GCC